
Card Present Architecture and Data Flow
This document provides a technical overview of the Card Present (CP) architecture within the Single Entry Point (SEP). It explores how physical terminals integrate with the Regional API to process secure transactions across Latin America.
High-Level Architecture
The SEP Card Present solution leverages the same infrastructure as e-commerce (Regional API) but replaces customer-entered card data with hardware-secured payloads.
Connectivity Topologies
| Topology | Data Flow Path | Use Case |
|---|---|---|
| Direct Integration | Terminal → Getnet Cloud | Standalone POS/mPOS where the device firmware is the API client. |
| Merchant Host | Terminal → Merchant Backend → Getnet Cloud | Integrated retail systems where a central server manages business logic and API orchestration. |
The Four Technical Pillars
The architecture relies on four fundamental components to ensure security and regional compliance:
- Terminal Identity: The
terminal_number,logical_code, andserial_number(anchored in theterminalobject) identify the physical source. - Secure Entry Modes: The
entry_mode(chip,chip_contactless,magnetic_stripe) dictates the required payload. - Hardware Payloads: Encrypted EMV TLV strings (for chips) or Track 2 (for swipe) generated inside the hardware secure enclave.
- PIN Security (DUKPT): When
online_pinis used, the DUKPT scheme ensures thepin_blockandksn(Key Serial Number) are transmitted securely.
Transaction Flows
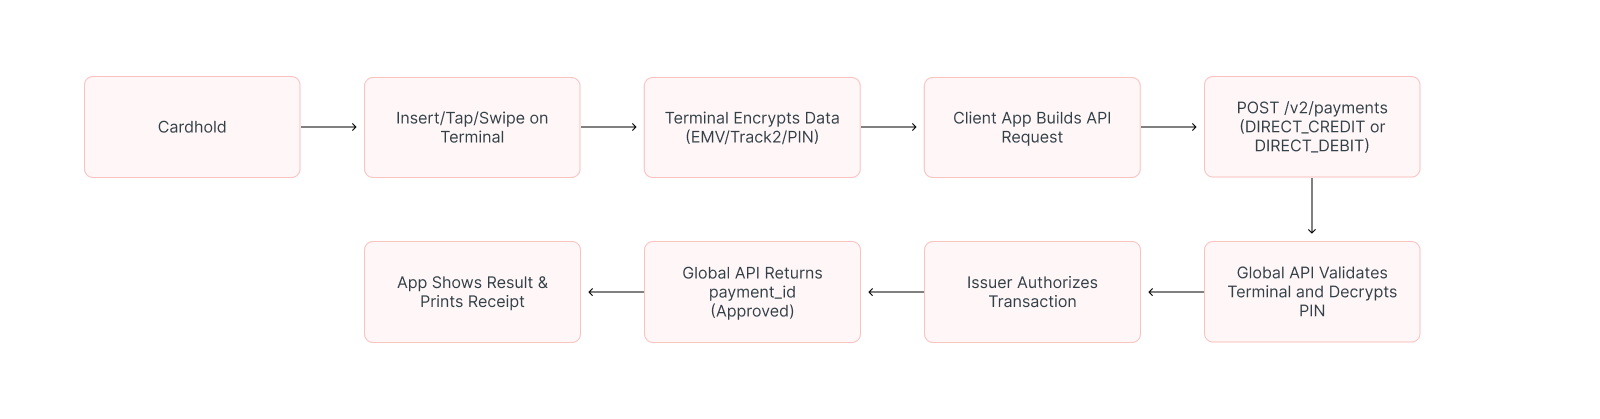
Single-Step Flow (Sale)
Standard flow where authorization and capture occur in a single API call using DIRECT_CREDIT or DIRECT_DEBIT.
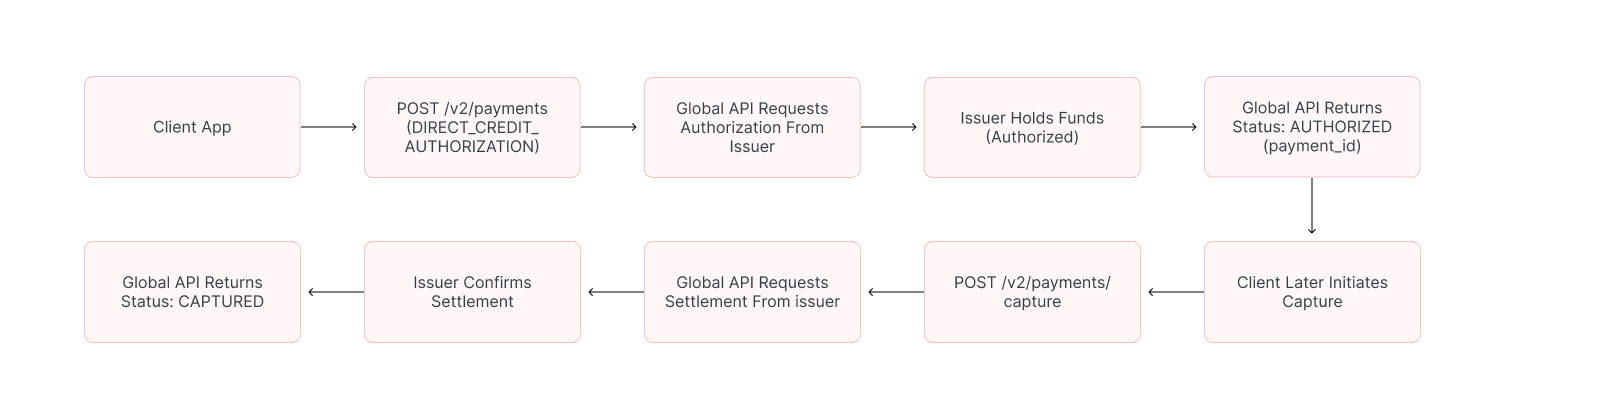
Two-Step Flow (Pre-Authorization & Capture)
Used for rentals or hospitality where the final amount is confirmed later.
QR Code Payment (Visa/Mastercard)
This flow is available for Visa and Mastercard QR payments on physical terminals.
Pix Payment (QR / NFC)
This flow generates a Pix QR Code at the terminal for Brazil (BRL) and confirms the payment asynchronously. The terminal displays the QR Code as a scannable image or presents it over NFC (contactless Pix).
- The terminal sends a
POSTrequest to the/qrcode/pixendpoint with the amount, currency, and customer identifier. - The API returns
201 Createdwith theqr_codeandqr_code_nfcpayloads (plusaids) and aWAITINGstatus. - The terminal renders
qr_codeas a scannable image or presentsqr_code_nfcover NFC. - The customer authorizes the payment from their banking app.
- Getnet confirms the payment asynchronously through the
PIX_UPDATED_TRANSACTIONSwebhook.
For the full request and response, see Create a Card Present Pix Payment.
Regional Variations
The architecture adapts to specific regional requirements defined in the API:
- Argentina & Chile: Feature a dynamic Installment Quotes endpoint (
/v2/payments/quotes) to fetch plans based on the card’s BIN. - Mexico: Use pre-defined installment plans directly in the payment request.
- Brazil: Supports terminal-initiated Pix (QR / NFC) payments via the
/qrcode/pixendpoint, where the customer authorizes the payment from their banking app.
Security & Compliance
- Liability Shift: By using EMV technology (Chip & PIN), the responsibility for fraud shifts from the merchant to the issuer.
- PCI-DSS Scope Reduction: Hardware encryption (P2PE/DUKPT) ensures the merchant environments never handle clear-text card data.
- End-to-End Encryption: Card data is encrypted at the point of interaction (POI) and only decrypted inside Getnet’s secure Hardware Security Modules (HSM).